What Coastal Home Buyers Should Check Before they Buy in Hilton Head Island, South Carolina
What Coastal Home Buyers Should Check Before they Buy in Hilton Head Island, South Carolina
Key Takeaways
- Look beyond price, finishes, and proximity to the beach.
- Review parcel-specific flood exposure, drainage, insurance, and storm history early.
- Inspect systems and materials that may be affected by salt air, humidity, wind, and water.
- Budget for the complete cost of ownership, not only the mortgage payment.
- Read association documents and compare recent closed sales before setting an offer price.
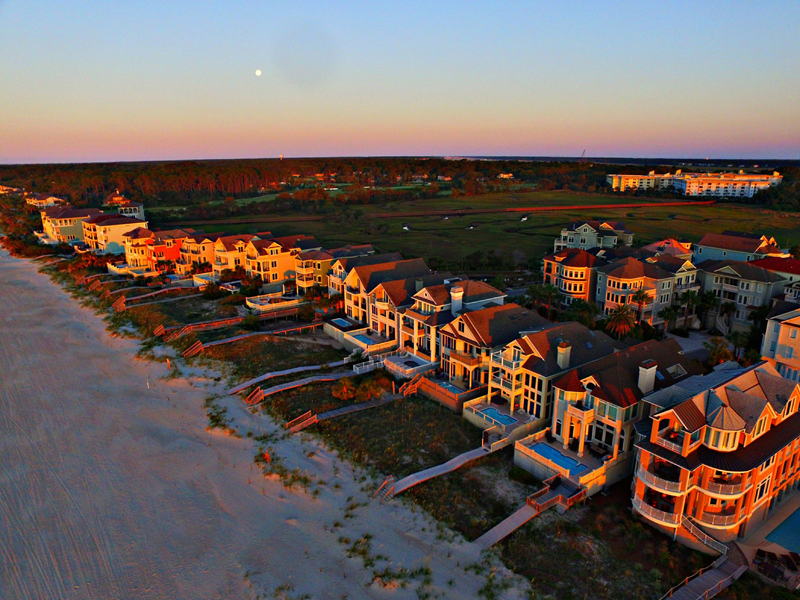
Buying near the ocean, marsh, lagoon, or golf course can make Hilton Head Island living feel distinctly Lowcountry. Still, a coastal purchase deserves more investigation than a quick tour and a strong first impression. Buyers exploring Hilton Head Island Homes for Sale can use Karen Ryan’s Hilton Head Island-focused property search for waterfront homes, condos, houses, rentals, and luxury options as a useful local starting point. Because Karen Ryan’s work centers on Hilton Head Island and nearby Lowcountry communities, the brand offers a relevant local real estate perspective for comparing property styles, neighborhoods, and ownership priorities. The right home is not simply the one with the best view. It is the one whose location, condition, insurance needs, community rules, and ongoing costs align with how you intend to use it. A little due diligence before an offer can prevent costly surprises after closing.
Why Coastal Homes Need Extra Review
Hilton Head Island properties can differ widely even when they appear similar online. A condominium close to the beach, a marsh-front house, and a home inside a gated golf community may each have different maintenance duties, insurance needs, access considerations, and association obligations. Coastal conditions can place added demands on roofs, HVAC equipment, exterior paint, fasteners, decks, windows, and drainage systems. Your intended use should guide the review. Full-time residents may prioritize grocery access, medical care, year-round services, and commute routes. Second-home buyers should consider travel logistics, security, and reliable property care while away. Buyers planning to rent should confirm local regulations, community restrictions, occupancy limits, and management costs before relying on projected income.
Study the Exact Location, Not Just the Neighborhood Name
Walk and drive the immediate area around the home. Check the route to beaches, shops, restaurants, medical offices, schools, and major roads. Visit at more than one time of day if possible, including a busy weekend or holiday period. Notice traffic, parking, noise, lighting, nearby construction, road access, and places where water may collect after rainfall. Also consider how the setting supports daily routines. Island, mainland, waterfront, gated, and golf-oriented locations can each offer a different balance of privacy, convenience, visitor activity, and maintenance responsibility. A property that feels perfect for a vacation week may not suit full-time living, and the reverse can also be true.
Review Flood Exposure and Insurance Early
Flood research should focus on the individual parcel rather than general statements about the area. Start with the property’s flood zone information, then ask whether an elevation certificate is available and whether the seller can provide records of water intrusion, drainage issues, storm damage, repairs, or insurance claims. The FEMA Flood Map Service Center can help buyers begin reviewing flood map information for a specific address. Request homeowners, wind, flood, and umbrella insurance quotes before important contract deadlines. Compare premiums, deductibles, exclusions, coverage limits, and the circumstances that trigger each policy. Online maps and estimates are useful research tools, but insurers, lenders, surveyors, inspectors, and local officials can provide more property-specific guidance.
Inspect for Coastal Wear and Deferred Maintenance
A general home inspection is essential, but some homes call for additional specialists. Carefully review the roof’s age and repair history; flashing; windows; doors; seals; shutters; HVAC corrosion; electrical panels; plumbing; crawl spaces; moisture; mold; and visible drainage issues.
Ask for additional evaluation when relevant
- Waterfront properties may warrant inspection of docks, seawalls, bulkheads, and retaining walls.
- Older homes may need closer review of major systems and prior renovation permits.
- Homes with pools, septic systems, extensive decks, or elevated structures may need specialized inspections.
- Condos require attention to both the unit and the building’s shared components.
Calculate the Full Cost of Ownership
Build a monthly and annual estimate that includes mortgage principal and interest, property taxes, insurance, association dues, utilities, pest control, landscaping, cleaning, and routine repairs. Add reserves for large expenses such as roofing, HVAC replacement, exterior maintenance, storm preparation, drainage work, or repairs not covered by insurance. For a rental or occasional-use home, include property management, turnover cleaning, furnishing, and vacancy-related costs. A lender’s approved amount is not necessarily the budget that will feel comfortable over time, especially when insurance or association costs change.
Compare Financing and Community Documents Carefully
Compare mortgage offers beyond the interest rate. Review loan terms, rate type, down payment, points, lender fees, closing costs, escrow estimates, and the total projected monthly payment. The Consumer Financial Protection Bureau explains how buyers can request and review multiple Loan Estimates that use comparable loan features and property cost details. If the property belongs to an HOA or condominium association, request the budget, reserve information, meeting minutes, governing documents, insurance details, current fees, and notice of planned projects or special assessments. Confirm rules for rentals, pets, parking, renovations, boat storage, and amenity use. Shared roofs, roads, drainage, pools, and recreation facilities can affect future costs.
Compare Recent Sales Before Making an Offer
Asking prices and automated valuations are only starting points. Compare recent closed sales with similar locations, property types, construction, condition, size, parking, storage, outdoor space, and access. Keep condos, townhomes, detached homes, waterfront properties, and inland homes in separate comparison groups whenever possible.
Questions to Ask Before You Commit
- What are the estimated annual insurance costs and deductibles?
- Has the property experienced flooding, water intrusion, or storm damage?
- How old are the roof, HVAC system, windows, and major appliances?
- Are there open permits, unresolved violations, or pending repairs?
- What fees, rules, projects, or assessments apply through the association?
- Which inspections and documents must be completed before contract deadlines expire?
A Simple Pre-Offer Checklist
- Define how you will use the home now and in the future.
- Visit the location at different times and test important travel routes.
- Review flood exposure, drainage, and insurance options.
- Estimate total ownership costs and available repair reserves.
- Read HOA or condo documents in full.
- Complete appropriate inspections and compare recent sales.
Final Thoughts
A Hilton Head Island home should be evaluated for more than its view, beach access, or interior finishes. Buyers who investigate location, insurance, maintenance, financing, community documents, and everyday convenience are better positioned to choose a property that supports both their lifestyle and long-term plans. It is also important to understand how the home’s age, construction, and exposure to coastal weather may affect future upkeep and ownership costs. Reviewing flood considerations, property restrictions, association fees, and any planned community improvements can help buyers identify expenses or limitations that may not be obvious during a showing. Visiting the property at different times can also provide a clearer sense of traffic, noise, access to services, and seasonal activity. By comparing these practical details with the home’s features and having qualified professionals review key records, buyers can make a more informed decision and prepare for the responsibilities of coastal homeownership.
Feature Image Source: Ben Baker via Pexels